Secured Business Finance

Borrow more, for longer and at a lower cost by putting commercial property or other business assets behind the loan. We arrange secured facilities from the banks, challengers and specialist lenders on our extensive panel.

Lorry at the loading bays of a distribution warehouse
Corporate Finance/Secured Business Finance
Funding from £25k to £25m+
Funding solutions tailored to your business and objectives
Up to 25 years
Typical term
Extensive lender panel
Access to high street, challenger, specialist and alternative lenders
Use Cases

What can secured business finance be used for?

Security lowers the lender's risk, which is why secured loans come with the largest sums, the longest terms and the keenest rates. The asset stays in use; the lender simply takes a charge over it.

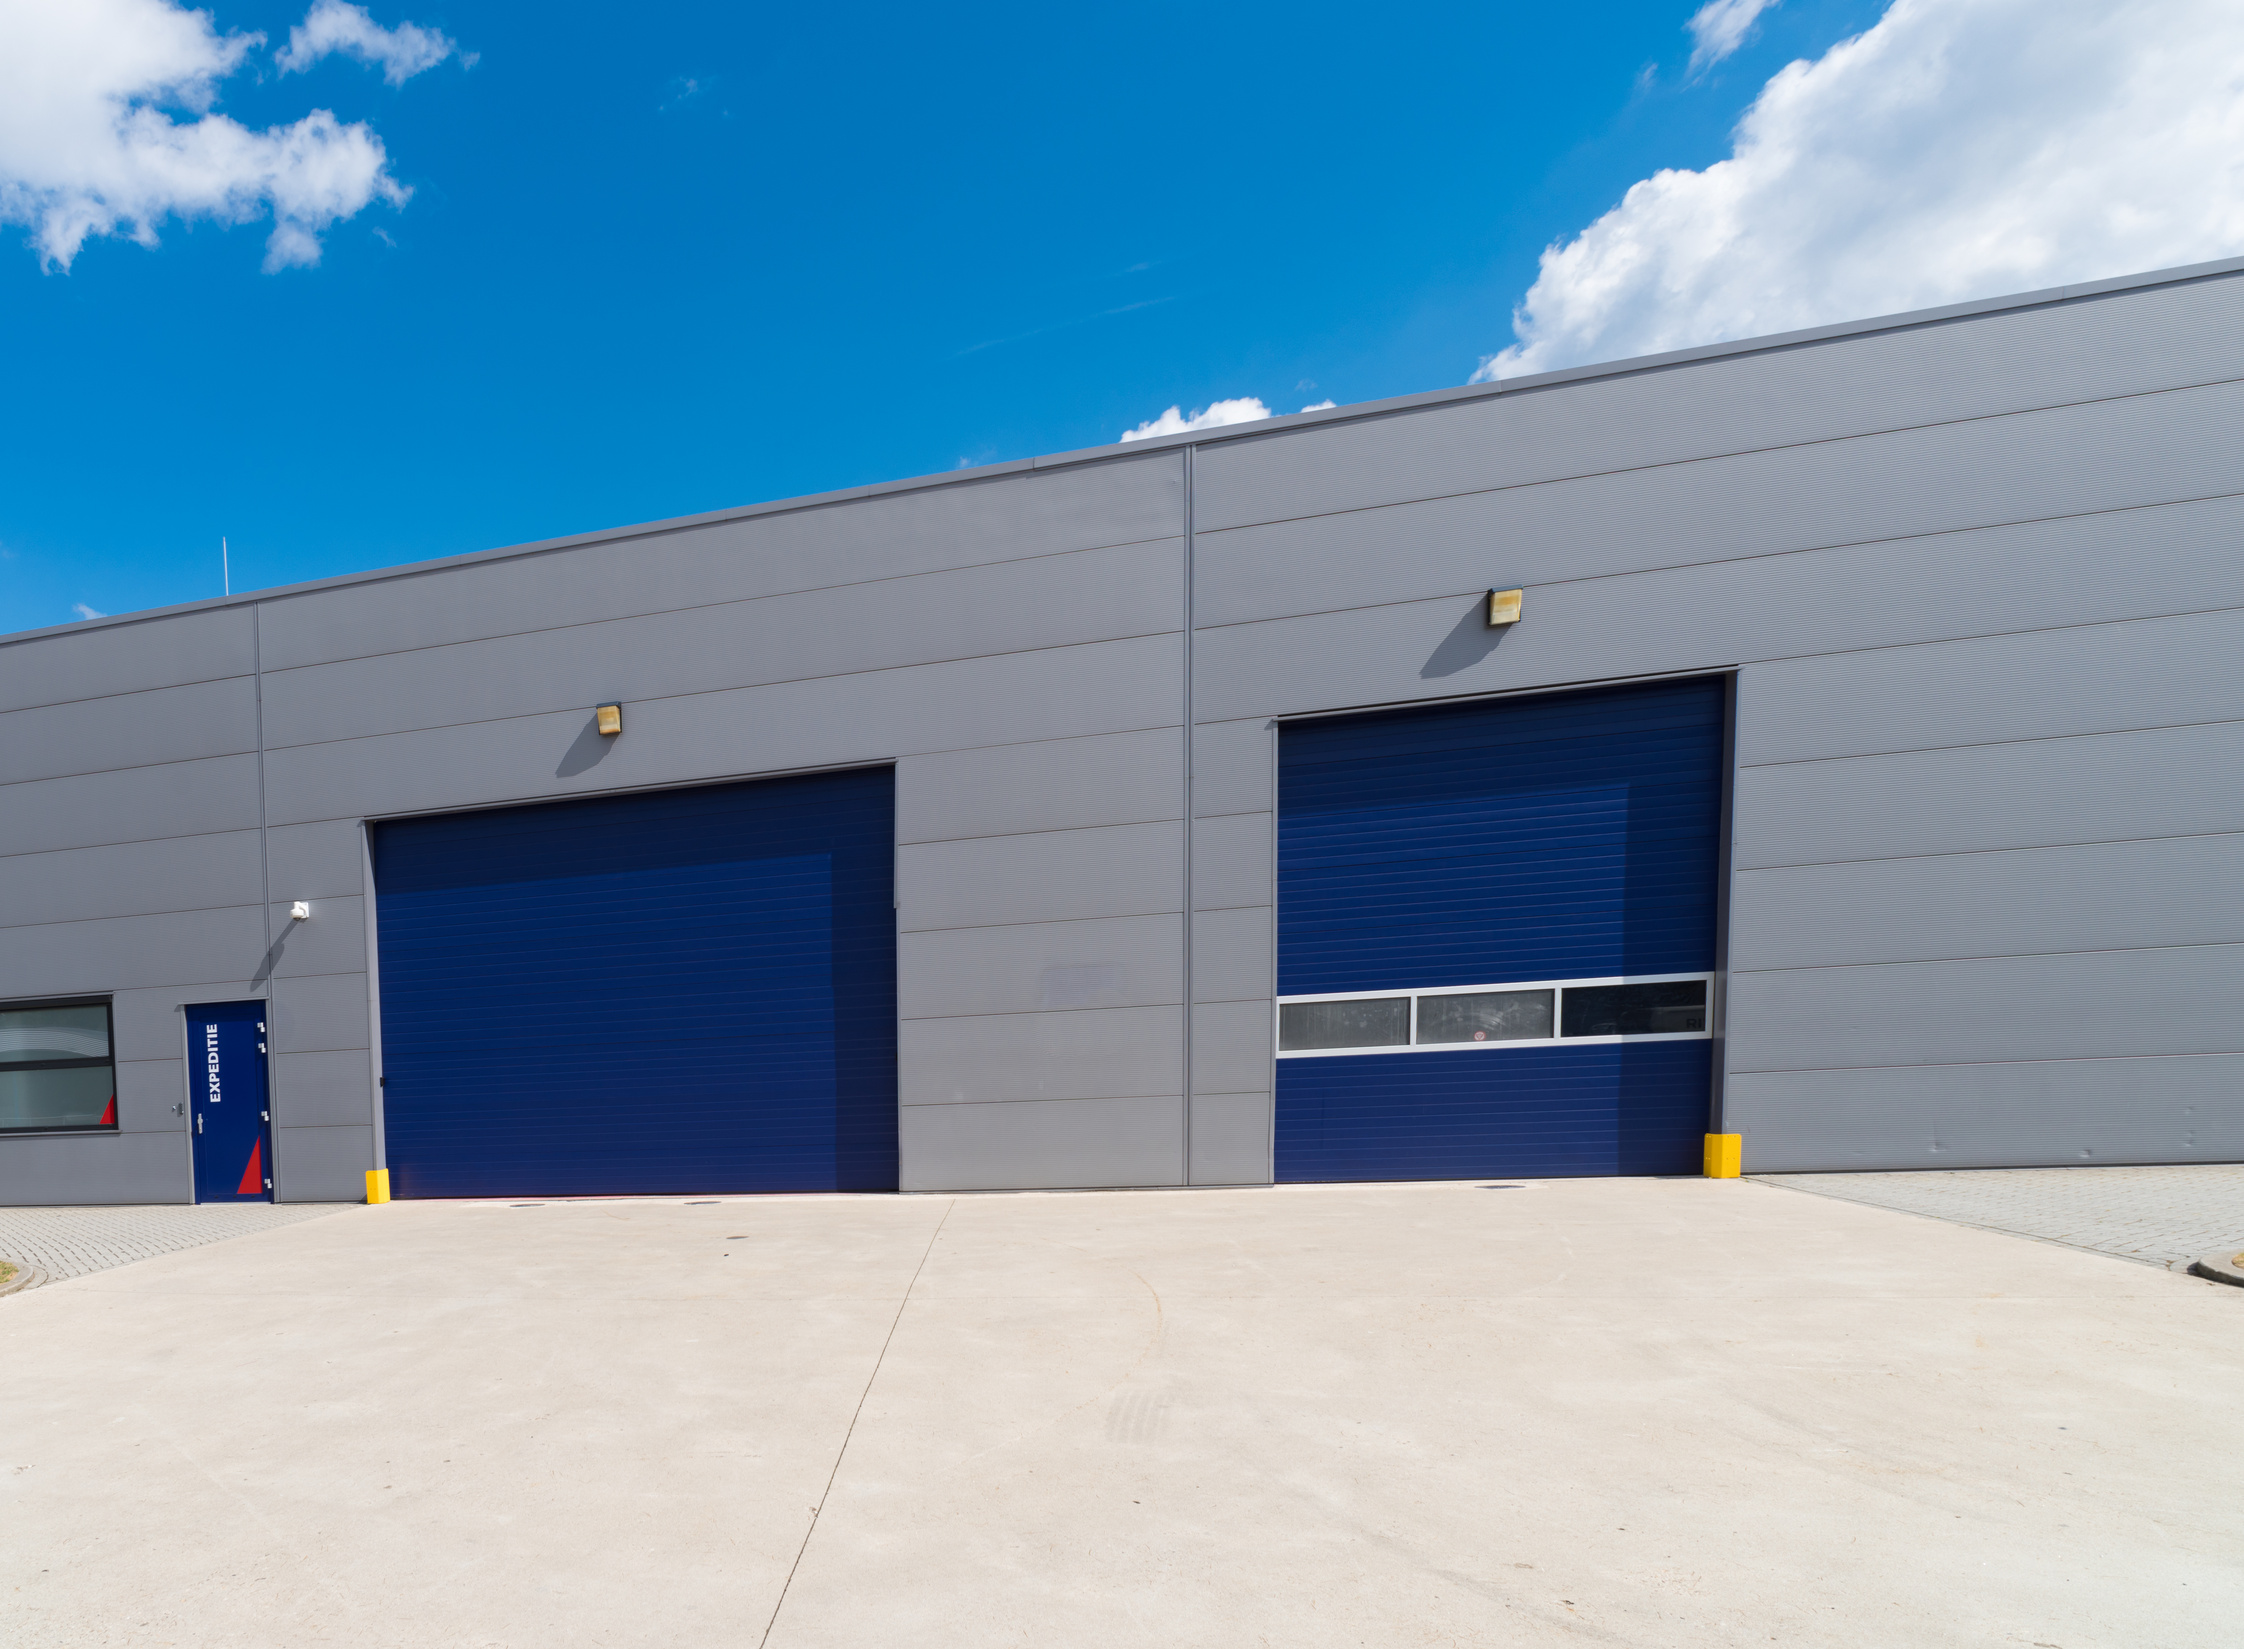
Modern industrial unit with loading bays
Releasing equity from premises

Raise capital against a freehold or long leasehold you already own, whether it is an office, warehouse, factory, care home or hotel, without selling or moving.

Workers on a car production line
Long-term investment

Fund a major fit-out, a new production line or a multi-year expansion plan over a term that matches the life of the investment, not the next twelve months.

Businesswoman using a calculator on company financial documents
Consolidating expensive debt

Replace a stack of short-term loans, merchant advances and overdrafts with one secured facility and a single, lower monthly payment.

Signing a facility agreement with a fountain pen
Larger one-off requirements

Acquisitions, buying out a partner, or settling a significant liability where an unsecured lender would cap the amount or the term.

Our Process

How secured finance comes together

Three steps, one adviser throughout. We tell you what to expect at each stage and what we need from you.

1
30 minutes · No obligation

Discovery call

We talk through what you need, what security is available and any existing charges over it. You leave with a view of the likely loan-to-value, term and pricing.

You bring: a rough value of the property or assets offered, details of any existing lending secured on them, and your last filed accounts.
2
Typically 1 to 2 weeks

Lender terms provided

We package the proposal, obtain indicative terms from the lenders best suited to your security and sector, and bring back a comparison on rate, term, fees and covenants.

You bring: management accounts, bank statements and any existing facility letters. A valuation is usually instructed once you choose a lender.
3
4 to 8 weeks, depending on legal work

Funds issued

We manage the valuation, the legal process and the lender's conditions through to completion, and stay alongside you until the facility is drawn.

You bring: a solicitor to act for you, signed documents and any information the valuer or lender asks for. We chase the rest.
Joel White, founder of Ramsay & White
Eligibility

What lenders look at

The security matters, but it is not the whole story. Lenders want to be repaid from trading, not from selling your assets. Four things shape the terms you are offered.

The security on offer

The value, condition and marketability of the property or assets, and the loan-to-value that leaves. Commercial property typically supports lending of up to 70% of value; specialist or trading-dependent premises less.

Trading performance

Filed accounts and recent management information showing the business can service the debt from its own cash flow, usually with headroom of at least 25%.

Existing charges and consents

Whether another lender already holds a charge over the asset, whether they will consent to a second charge, and how the new facility ranks against existing borrowing.

Purpose and exit

What the money is for and how the lender gets repaid: through amortisation over the term, a refinance, or a sale of the asset. Clear purpose, clear exit, better pricing.

Common structures

Secured term loan, commercial mortgage or second charge?

Three structures cover most secured lending. The right one depends on whether the property is the purpose of the loan or simply the security for it, and whether there is already a lender in place.

Secured term loan
Borrow against assets you own
Commercial mortgage
Buy or refinance premises
Second charge loan
Raise more behind an existing lender
Secured on
Property, plant, stock or debtors
The property being bought or refinanced
Property with an existing first charge
Typical loan-to-value
Up to 70% of property value, less on other assets
Up to 75% of value, higher for owner-occupiers
Up to 70% combined across both charges
Term
1 to 10 years
5 to 25 years
1 to 10 years
Cost
Low. Priced on security and trading
Lowest, longest and most competitive
Higher than a first charge, lower than unsecured
Speed
4 to 8 weeks
6 to 12 weeks
4 to 8 weeks, subject to first lender consent
Best for
Growth capital or consolidation without moving your banking
Buying premises or refinancing an existing mortgage
Raising capital when your current lender will not lend more

*Indicative only. Loan-to-value, rates and terms depend on the lender, the asset and your trading position. Commercial mortgages are arranged through our property finance team.

Will Roberts, Managing Director Corporate Finance at Ramsay & White

Get secured finance terms

Tell us what you need to raise and the security you have available, and one of our corporate finance advisers will call you back, usually the same working day.

By clicking Submit you're confirming that you agree with our Privacy Policy.
Form sent successfully.
Our team member will be in contact with you shortly.
Something went wrong while submitting the form. Please try again.

Client Testimonials

Hear what business owners and property investors say about working with Ramsay & White.

Worked for Joel and the whole team for over 4 years now. Residential, commercial and bridging finance. Always super professional, quick, efficient, helpful and on the end of a call anytime. Highly recommended and we see them as an extension of our own team.

Steven Pardoe

Outstanding, efficient and effective service by Will and Joel. Regular updates, clear and precise. Highly recommended for a smooth, friendly professional service for your lending requirements and financing advice.

Steve Dury

Have worked with Paul and Rachel on several transactions. They have always been extremely knowledgeable, highly responsive and provided excellent service from start to finish.

Matt Barrow

Having done a number of deals with R&W I would highly recommend them! I have been very impressed with their professionalism and knowledge. They are efficient and very helpful, they have helped me grow my business very quickly over the last few months, doing multiple deals at the same time. I Can’t wait to carry on our journey together.

Harvinder Sull

We have been using Ramsay & White as our brokers for a number of years now. They have covered all of our lending requirements from buy-to-let, commercial to bridging. The knowledge and professionalism are second to none. I would highly recommend Ramsay & White.

Jeannette Linfoot

Thanks to Will and Olly. Very professional, responsive and efficient. I would highly recommend Ramsay & White!

Jonathan Lewis

I have used Ramsay & White for several years, they're so helpful and knowledgeable and have always given me the best advice which I would say is invaluable. When using their services I am always being updated at every point throughout the process. I want to say a massive thank you to Joel White & Will Roberts. I've had nothing but an incredible experience from you and I look forward to carrying on working with you in the future.

Charlie Slocombe-Smith

A great service provided by Ramsay and White. Would highly recommend.

Ben Grover

I outgrew my previous IFA and was in need of a company to take my business to the next level. From the outset these guys were professional and clearly experienced working with property investors. They managed to assist with my refinance and I will continue to use Ramsay & White to assist with growing my portfolio through my LTD company.

Ashley Matthews

Secured Business Finance FAQs

Answers to the questions business owners ask us most about secured lending.

What counts as security for a business loan?

Most commonly commercial property, but lenders will also take security over plant and machinery, stock, debtors and, in some cases, a debenture over the whole business. The stronger and more saleable the security, the better the terms.

How much can I borrow against commercial property?

Typically up to 70% of the property's value, sometimes more for owner-occupied premises with strong trading behind them. Specialist or trading-dependent property such as care homes and hotels is usually valued on the business as well as the bricks and mortar.

Can I raise money against premises I already own?

Yes. Releasing equity from a freehold or long leasehold is one of the most common uses of secured finance. The loan can fund investment, consolidate debt or provide working capital, and the property stays in your ownership.

Does my existing lender need to agree?

If another lender already holds a charge over the asset, they will usually need to consent to a second charge or be repaid as part of the new facility. We manage that conversation as part of the process.

How long does secured finance take to complete?

Usually four to eight weeks, driven mainly by the valuation and legal work. Refinancing an existing facility can be quicker; a first charge on property you have never borrowed against takes longer.

What terms are available?

Secured term loans typically run from one to ten years; commercial mortgages up to 25 years. Interest can be fixed or variable, and some lenders offer interest-only periods for larger investments.

Is secured finance cheaper than an unsecured loan?

Almost always, because the lender's risk is lower. Against that, you should factor in valuation and legal costs and the time it takes to complete. We show you the total cost of each option side by side.

Have More Questions?
Schedule a Call with our Team

News & Updates

Latest on Business Finance

Explore our latest business funding insights, case studies and news.

£1.85m Business Acquisition Loan Secured

£1.85m Business Acquisition Loan Secured

Ramsay & White secured a £1.85m acquisition loan, enabling a client to purchase a fast-growing haulage company and accelerate their expansion in the logistics sector.
Ramsay & White Launches Business Funding Arm for SME's

Ramsay & White Launches Business Funding Arm for SME's

We are happy to announce that we can now secure a range of business funding solutions to help small to medium-sized businesses. This comes at a...
Coronavirus Business Loan – Key Features and How to Apply

Coronavirus Business Loan - Key Features and How to Apply

With Coronavirus causing an economic and health crisis, many businesses have found themselves unexpectedly in a tough situation. If your business is...

Why Ramsay & White?

At Ramsay & White, it’s not just about transactions; it’s about forging lasting relationships and being a steadfast companion in your journey towards financial prosperity.

a tall building with a street light in the middle of it

Ramsay & White Corporate Finance is a trading name of Ramsay & White Corporate Finance Ltd, which is an Appointed Representative of New Leaf Distribution Ltd, authorised and regulated by the Financial Conduct Authority, FCA number 460421. Ramsay & White Corporate Finance is a credit broker and not a lender. We work with a panel of lenders to find you a potentially suitable arrangement for consideration. ICO registration ZC246341, which you can check via www.ico.org.uk. Registered address: 7 Soundwell Road, Staple Hill, Bristol, United Kingdom, BS16 4QG. Registered in England & Wales. Registration number: 17450526.

We will receive commission from lenders. Different lenders pay different amounts depending on different commission models. For transparency we work with the following commission models: fixed fee, fixed rate of commission, percentage of the amount you borrow and rate for risk (this is based on the risk profile of the application). Further details of the commission model, calculation and amount will be disclosed to you throughout your customer journey.